Road debris damage in Malaysia: who is responsible?
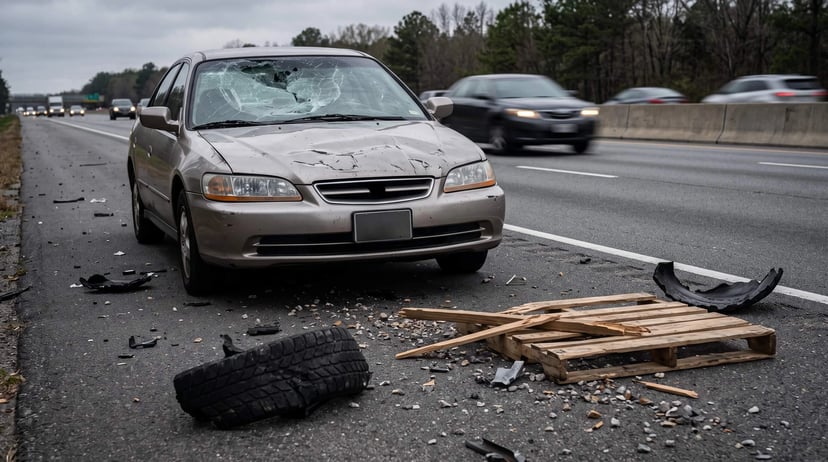
Who is responsible when road debris damages your car in Malaysia?
When road debris damages your car in Malaysia the person who is responsible can be the driver who dropped the debris the contractor whose work caused the debris or the highway operator who did not keep the road safe. The answer depends on the evidence. Your car insurance might also cover the damage. This depends on your policy and its exclusions.
A loose tyre, fallen cargo, construction material or stone thrown up during maintenance can cause expensive damage, in seconds. Knowing what to do away can help you keep evidence find the responsible party and increase your chances of getting repair costs back.
Key takeaways
Liability depends on the circumstances: The driver responsible for unsecured cargo, a negligent contractor or a highway operator that failed to take reasonable safety measures may be held liable.
Evidence matters: Photograph the damage, road debris, location and relevant warning signs, and preserve your dashcam footage.
Report the incident promptly: Make a police report within 24 hours where required for a road accident and notify your insurer as soon as possible.
Check your insurance policy: Comprehensive motor insurance may cover accidental damage to your own car, subject to the policy terms, excess and exclusions.
Keep your vehicle records organised: Motorist App can complement your ownership routine, while your insurer and relevant road authority remain the main contacts for claims and road hazards.
Who pays when road debris damages your car?
There is no rule that declares every road authority or highway concessionaire automatically liable, for road debris damage. The key question is who caused the hazard, who had the duty to manage it and whether negligence can be proven.
1. Another driver who dropped or carried the debris
The driver could be held responsible if evidence shows that the driver’s negligence caused the debris to fall onto the road and damage your car. Examples of debris include unsecured construction materials, loose furniture or cargo that was not properly fastened to a vehicle.
Write down the vehicle’s registration number, the type of cargo and any dashcam footage you can get. If the driver leaves the scene hand the details and evidence you have over to the police of trying to chase or confront the driver.
2. A highway operator or road authority
A highway operator can be responsible if it didn't do what was needed to keep the road safe. Important information might include how long the debris stayed there if the operator knew about the danger and if they tried to check or remove it.
Malaysian court rulings have shown that the operator can be held responsible in some situations where there was debris on the road. For example a 2024 Sessions Court case involving Projek Lebuhraya Usahasama Berhad and Edgenta Propel Berhad dealt with an accident caused by debris and not keeping the road in condition.. Being responsible depends on the details and the proof, in every case.
If the accident happens on a highway that charges a fee write down the name of the highway the direction you were going the closest exit and the kilometer marker. Tell the highway operator about the incident. Request an incident reference number.
3. A road maintenance or construction contractor
A contractor can be held responsible if the work that the contractor does creates a hazard. If the contractor does not take reasonable safety precautions. For example stones that are thrown up by grass‑cutting equipment can damage cars that are passing if the work area is not properly protected.
Where possible write down the contractor name, vehicle registration, equipment and work location. Do so without putting yourself in danger. Also notify the highway operator or road authority because the contractor and the operator may have different responsibilities.
4. What if nobody can be identified?
If there is not evidence to prove that another party is responsible you may have to rely on your own insurance. Whether your insurance policy covers the incident depends on the policy terms the type of damage and any exclusions that may apply.
Bank Negara Malaysia says that you can file a claim for damage to your vehicle, under a comprehensive insurance policy but only if the policy terms allow it. Keep in mind that an own‑damage claim may reduce your No Claim Discount (NCD). Check with your insurer for the consequences before you move forward.
What should you do if road debris damages your car?
Follow these steps to protect yourself, your vehicle and any potential claim.
Step 1: Stop somewhere safe
Do not suddenly stop in the middle of a moving traffic lane to look at the damage. If your car is still under control slowly move to the side of the road or, to an area. Turn on your hazard lights. Check around you for any danger.
If your windscreen has a crack if a tyre is damaged or if your car feels wobbly or hard to steer don’t keep driving if it’s not safe. Call for roadside help. Get your car towed if needed.
Step 2: Photograph the scene and damage
Capture evidence before the debris is removed if you can do safely. Take photographs of the damaged parts, the debris, the road surface, nearby signs and the wider scene.
Record the date time, direction of travel and nearest kilometre marker or identifiable landmark. Save your dashcam recording and make a backup before the camera overwrites it.
Step 3: Identify the responsible party
Look for proof that connects the debris to a person, vehicle, contractor or road operator. A registration number, a witness statement, a dashcam recording or a maintenance-work sign could help show what happened.
Don’t jump to conclusions just because the incident happened on a highway or, near roadworks. Call the operator, authority or contractor to report what happened. Ask them how to send your evidence.
Step 4: Make a police report and notify your insurer
Report the incident quickly. Follow your insurer’s claims process. In Malaysia the Road Transport Act 1987 requires drivers involved in road accidents to report the incident within 24 hours unless specific legal exceptions apply.
Provide an factual description of what occurred. Include your photographs, videos and precise location details. Notify your insurer soon as possible even if you plan to seek compensation, from the other party.
Step 5: Obtain a repair assessment
Obtain a written quotation or assessment before authorising repairs unless urgent work is needed to keep the vehicle safe.
Ask the workshop to itemise the damaged parts the labour and any related work. Keep the quotation the invoices, the towing receipts and any inspection report. Your insurer or the party you are claiming against may require an inspection before repairs proceed so confirm the process first.
Step 6: Submit your claim and retain the records
I know this can feel overwhelming so pick the claim route that matches your evidence, your policy and the insurer’s advice. You can file a claim under your comprehensive policy or pursue the party who is legally responsible for the damage.
Keep copies of your police report claim reference, correspondence, photographs and repair documents. If the claim is rejected or liability is disputed ask the insurer to give the reasons, in writing and consider getting advice.
Can you claim against a highway concessionaire in Malaysia?
Yes it is possible to claim compensation from a highway concessionaire if the evidence shows that negligence of the highway concessionaire caused your loss. However a claim is not automatically successful simply because debris was found on a toll road.
A reported incident, in 2024 shows how the process can work: a Mercedes-Benz A-Class owner said that a stone thrown by roadside grass‑cutting work cracked the windscreen while travelling on the North‑South Expressway. The owner documented the scene obtained the contractor’s details and made a police report before pursuing the matter with PLUS.
The practical lesson is to preserve evidence and report the incident to the operator. Ask about the claims procedure of the operator the supporting documents that are required and whether the vehicle must be inspected before repairs.
Does car insurance cover road debris damage?
Comprehensive car insurance may cover accidental damage caused by road debris, but the actual coverage depends on your policy wording, exclusions and circumstances.
| Insurance consideration | What you should know |
|---|---|
| Comprehensive cover | May cover accidental damage to your own car, subject to policy terms |
| Third-party-only cover | Generally does not cover accidental damage to your own vehicle |
| Own-damage claim | May affect your NCD, depending on the claim and applicable rules |
| Third-party claim | May be possible if you can establish another party's liabilty |
| Windscreen damage | Check whether the damage is covered by your policy or a separate windscreen benefit |
| Excess or deductible | You may have to pay an amount specified in you policy |
| Repair approval | Your insurer may require an inspection or authorisation before repairs |
Important: Do not assume that every stone chip, punctured tyre or damaged underbody component will be covered. Check the exact policy wording and ask your insurer whether the particular damage is covered before committing to repairs.
Old way vs. Motorist App: keeping your car records organised
When an unexpected incident occurs, having your vehicle details and ownership information organised can make the follow-up process easier. Motorist App is a useful companion to your regular car-ownership routine, but it does not replace a police report, an insurance claim or evidence linking the debris to a responsible party.
| Task | Handling everything manually | Using Motorist app alongside your claim |
|---|---|---|
| Vehicle ownership routine | Keep vehicle details and document in separate places | Use the app as a companion for managing your car-ownership needs |
| Incident evidence | Collect photographs videos and receipts yourself | Continue collecting and backing up original evidence separately |
| Damage assessment | Obtain a workshop quotation | Obtain the same written quotation and retain it for your claim |
| Reporting deadline | Track the applicable 24-hour reporting requirement yourself | Set your own reminder; do not assume the app files a police report |
| Repair cost | Depends on the actual damage and repair assessment | No guaranteed savings or fixed repair price |
| Compensation | Depends on evidence, liability and insurance terms | The app does not guarantee compensation or determine liability |
The important distinction: Motorist App can complement your vehicle-ownership routine, but there is no fixed app fee, repair price or compensation amount that applies to every road debris incident. Your actual costs depend on the damage, insurance excess and outcome of any claim.
Expert tip: preserve the original dashcam footage
The dashcam recording is essential so please save the unedited dashcam recording as soon as possible and include the minutes before and, after the impact. The lead‑up may show where the debris came from whether another vehicle dropped it or whether roadside work was taking place.
Create a backup and note the exact timestamp. A short clip showing the impact may not establish who caused the hazard while the surrounding footage could provide useful context.
Common mistake: repairing the car before documenting the damage
Do not throw away the pieces replace your dashcam video or approve any repairs that are not urgent, before gathering proof and looking at what your insurance company says. Taking the proof away soon can make it more difficult to find out what caused the damage or back up a claim.
If the car needs repairs to stay safe take pictures of the damage if you can save the repair documents and talk to your insurance company right away.
Conclusion
When road debris damages your car in Malaysia, responsibility depends on who caused the hazard, the circumstances and the evidence available. Document the incident, report it promptly, notify your insurer and use Motorist App as a companion to your car-ownership routine.
FAQs
1. Who is responsible if road debris damages my car in Malaysia?
The driver who dropped the debris, a negligent contractor or a highway operator may be liable, depending on the circumstances and evidence. You may also need to claim under your own insurance policy.
2. Can I claim compensation from a highway concessionaire?
Yes, if you can establish a legal basis for the claim, such as negligence by the concessionaire. Photographs, dashcam footage, location details and witness accounts may help support your case.
3. Does comprehensive car insurance cover road debris damage?
It may cover accidental damage to your own car, subject to your policy's terms, exclusions and excess. Contact your insurer to confirm coverage for the specific damage.
4. Does third-party car insurance cover damage to my own car?
Generally, no. Third-party-only motor insurance primarily covers qualifying liabilities to other parties rather than accidental damage to your own vehicle.
5. Do I need to make a police report if road debris hits my car?
You should report the incident promptly and comply with the applicable legal requirements. For road accidents in Malaysia, a 24-hour reporting requirement generally applies to drivers involved in an accident.
6. What evidence should I collect after road debris damages my car?
Take photographs of the damage, debris, road conditions and location. Preserve the original dashcam footage, note witness details and keep the police report, repair quotation and receipts.
7. Can I claim if I do not know where the debris came from?
You may still be able to claim under your own comprehensive policy if the incident is covered. A claim against another party may be more difficult if there is insufficient evidence to identify them or establish liability.
8. Will a road debris insurance claim affect my NCD?
It can, particularly if you make an own-damage claim under your comprehensive policy. Ask your insurer whether the proposed claim will affect your NCD and whether another claim route is available.
9. What if road debris damages only my windscreen?
Check your policy's windscreen coverage and exclusions. If the damage was caused by a contractor or another identifiable party, preserve the evidence and consider reporting the incident to the responsible party as well.
10. Should I repair my car before making an insurance claim?
Contact your insurer first and confirm whether an inspection or authorisation is required. Document the damage and obtain a quotation before proceeding with non-urgent repairs.
11. Can Motorist App help if road debris damages my car?
Motorist App can complement your vehicle-ownership routine, but you must still document the incident, report it where required and contact your insurer or the relevant road operator to pursue a claim.
Keep your car ownership organised with Motorist App
Read More: Is it illegal to drive barefoot in Malaysia? Fact or fiction?
I want to find the highest selling price for my car within 24 hours!
Download the Aplikasi Motorist now. Designed by drivers for drivers, this all-in-one app lets you receive the latest traffic updates, gives you access to live traffic cameras, and helps you manage vehicle related matters.